On this page
- Shift 1: Video budgets fragment, and reallocation follows proof
- Shift 2: Generation got cheap, judgment got scarce
- Shift 3: Buyers started auditing delivery
- Shift 4: Outcome pricing became a buying option
- Shift 5: Disclosure moved into the brief
- The thesis underneath
- What this means, by seat
- Three questions worth asking this quarter
- FAQ
- Sources
U.S. digital video ad spend is projected to pass $80 billion in 2026, social video has taken the growth lead, and CTV budgets are being rebid on evidence. Generation costs collapsed, so brief quality became the constraint. Among buyers on publisher-direct and programmatic guaranteed deals, 43% lack high confidence in where their ads ran. CTV can now be bought on cost per outcome, and New York made disclosure of AI-generated synthetic performers in ads a legal requirement.
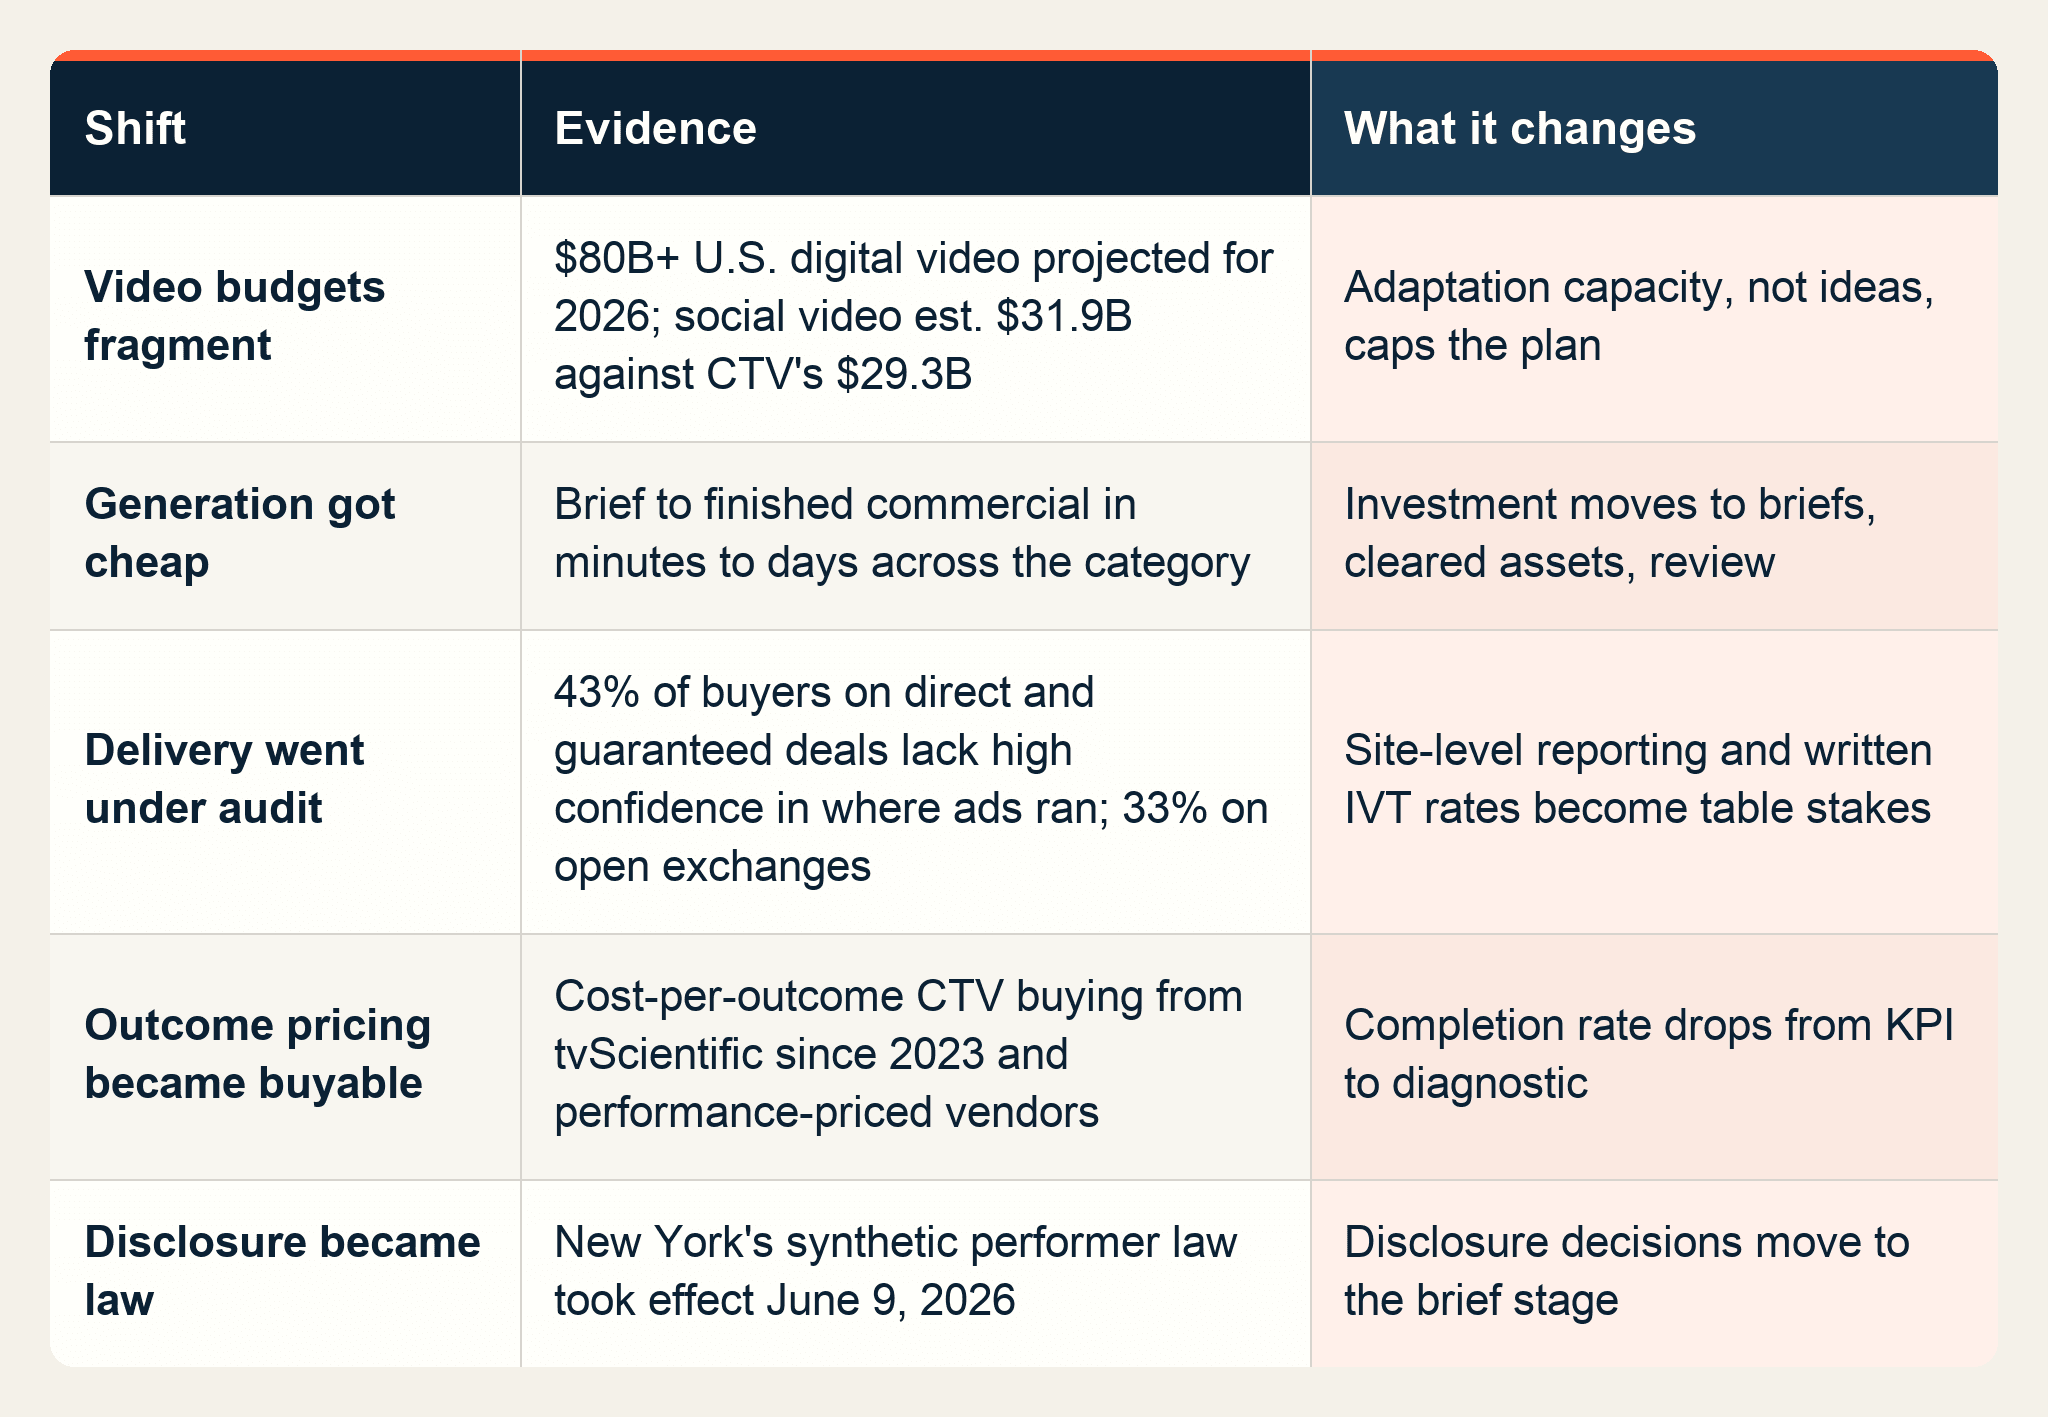
Across all five, advantage in TV advertising has moved from media access to the outcome loop, the cycle connecting which message, shown to whom, drove what result, and what to try next. Media access got commoditized. The loop did not.
Shift 1: Video budgets fragment, and reallocation follows proof
Per the IAB's 2026 Digital Video Ad Spend & Strategy report, published July 14, 2026, U.S. digital video ad spend is projected to pass $80 billion this year, up about 11%. Inside that total, social video is estimated at $31.9 billion against CTV's $29.3 billion, having overtaken CTV in 2025. Online video is estimated at $20.7 billion.
For budget planning, our 2026 TV commercial cost guide separates production, linear airtime, and streaming CPMs.
Video budgets are fragmenting across feeds, streaming apps, and web players, each surface with its own creative spec, and incremental dollars are judged on cost per result rather than reach.
What it changes: the workload math. One campaign across two lengths, three formats, four audiences and two languages is 48 versions of a single idea. Most creative teams are staffed to produce the idea, not the 48 versions. A 2026 plan that adds surfaces without adding adaptation capacity is fiction.
Shift 2: Generation got cheap, judgment got scarce
In 2024, AI video ads meant demos. In 2026 it is shipped product. MNTN released QuickFrame AI 3.0 on May 5, 2026, positioned as brief to finished commercial in minutes with publishing paths built in, and a set of AI studios, ours included, turn a brief into TV-ready video in days. Rendering speed stopped being anyone's advantage. Once 50 variants can be generated overnight, generating variants is not the edge.
The bottleneck moved to both ends of the process. Upstream is deciding what is worth saying: campaign goal, audience, product truth, brand rules. Downstream is deciding what is worth funding. Teams that hand an AI system a one-line prompt get generic output and conclude the technology is not ready. The model was fine. The brief was empty, and a human crew would have failed with the same brief.
The practical control layer is the AI video workflow around the model: reference roles, approval checkpoints, targeted revisions, and a record of what the next test should change.
What it changes: where the investment goes. The scarce inputs in 2026 are structured briefs, cleared brand assets, and a record of what already worked. Audit the creative operation the way a media plan gets audited: does the system know the product's real claims, does it remember the last ten winners, does a human review before anything ships. That is the shape of what we built AI Studio around: one campaign brief carried through production with a review gate at every stage, so decisions already signed off stay signed off when a scene gets remade. The wider workflow is in the AI creative loop for app UA.
Shift 3: Buyers started auditing delivery
The same IAB report puts a number on something the market has muttered about for years. Even on the most trusted paths, meaning publisher-direct insertion orders and programmatic guaranteed deals, only 57% of buyers report high confidence in inventory transparency, so 43% do not. Publisher-direct buying through self-service sits at 56%. On open exchanges it drops to 33%. Targeting capability has passed content quality as the top criterion for where budget goes, at 49% against 46%. Starti's guide to CTV audience targeting covers the signals behind each option.
Fraud protection is moving into the base cost of an impression, and premiums now have to be earned with evidence.
Measurement moved in the same direction. The deterministic-tracking era trained advertisers to expect click-level certainty. Privacy rules ended that expectation elsewhere in digital, and in 2026 CTV stopped claiming an exemption. A mature stack now layers deterministic attribution where it genuinely exists, meaning device-level exposure matched to installs through MMP integrations, then holdout tests once spend clears testing levels, then media-mix modeling above that. Less certainty, more defensibility. Starti's guide to CTV ad measurement covers what each layer can attribute.
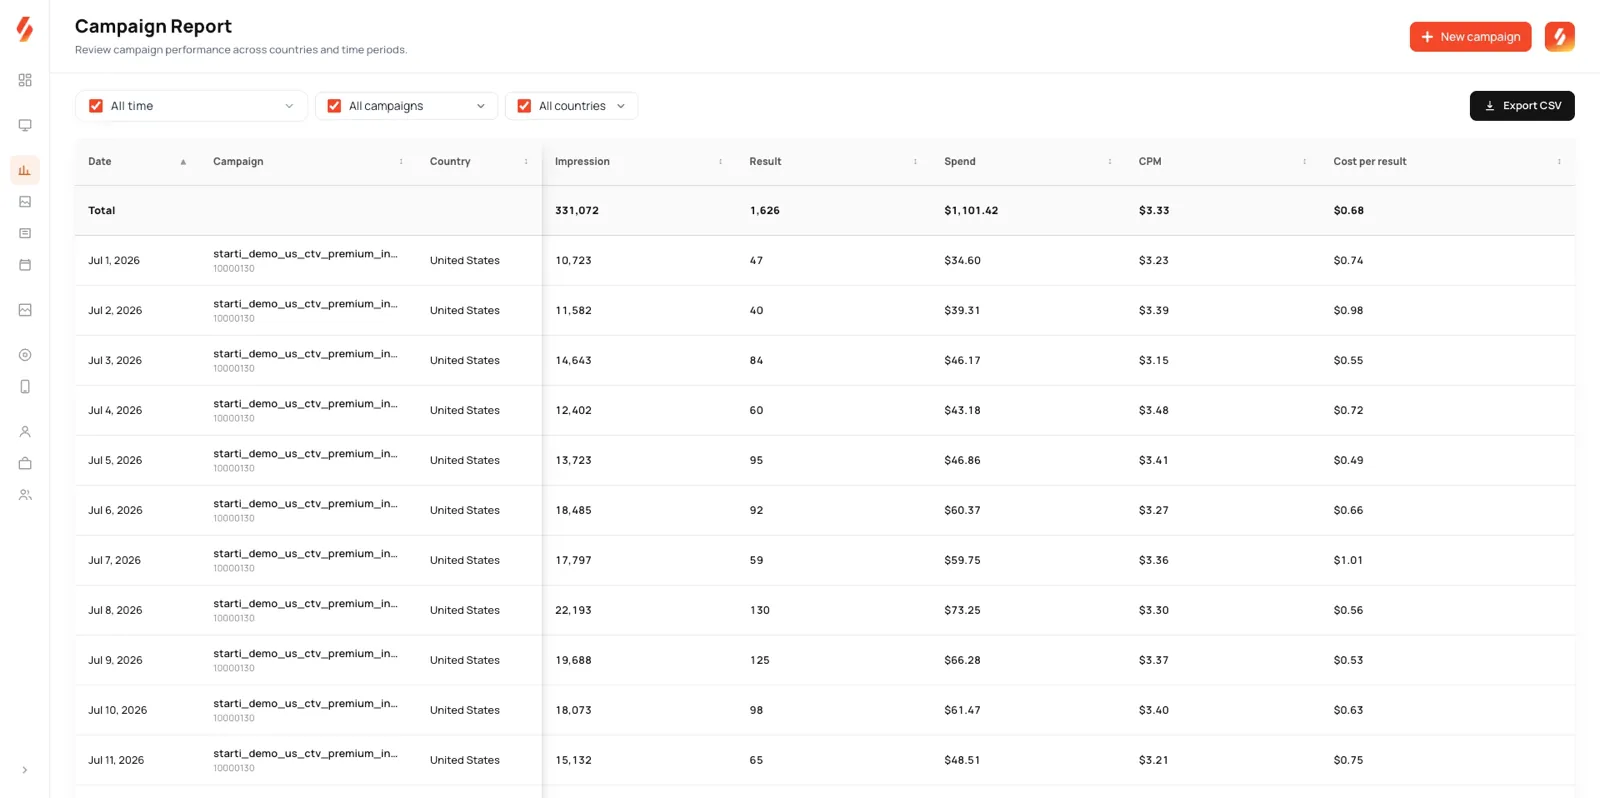
What it changes: what gets demanded in every platform conversation. Site-level delivery reporting, invalid traffic rates in writing per campaign, and attribution that reaches a business outcome. We publish our own rates for that reason: the Strava campaign ran under 1.1% invalid traffic across 41M+ impressions. A platform that cannot show delivery at that grain is selling reach, which is a legitimate purchase as long as it is priced as reach.
Shift 4: Outcome pricing became a buying option
For two decades TV sold on proxies: gross rating points, then impressions, then video completion rate. The alternative is now buyable. tvScientific has sold CTV on cost per outcome since 2023, where the advertiser defines the conversion and pays when it happens. Performance-priced models, ours included, tie media cost to installs, signups and revenue. Even MNTN's Performance TV positioning concedes the frame.
An 85% completion rate on inventory that goes unwatched is still wasted budget. Completion confirms playback, and playback was never evidence of persuasion. The industry knew that and priced on it anyway, because nothing better was operational. Something better is now operational, and the pricing pressure runs one direction.
What it changes: which number anchors the plan. Completion rate becomes a delivery diagnostic rather than a result, and the KPI that survives review is the one tied to revenue. Why 2026 is the year of outcome-based advertising covers the buying mechanics.
Shift 5: Disclosure moved into the brief
New York's synthetic performer law (S8420-A/A8887-B) was signed on December 11, 2025 and took effect June 9, 2026. An ad that includes a synthetic performer, meaning an AI-generated human who is not recognizable as a real person, must disclose it conspicuously when the person creating the ad knows it is there. Penalties are modest at $1,000 for a first violation and $5,000 after. The statute sets no geographic limit on the ads it covers.
By the time a lawyer sees the cut, the decisions that matter are already made: whose likeness, what consent, which claims. Disclosure is a creative-workflow step with legal consequences.
What it changes: the production pipeline. Teams that place the disclosure decision at the brief stage, before generation rather than after review, traffic faster, because nothing gets pulled at the last gate. New York is rarely the last state to act, so build for the pattern rather than the statute.
The thesis underneath
Put the five together and they describe one migration. Money is growing and fragmenting. Making ads got cheap. Delivery went under audit. Outcomes became purchasable. The workflow acquired legal checkpoints.
Each of those moves value away from media access, the inventory and buying advantages that defined ad tech for fifteen years, and toward the question of which message, in front of whom, drove what result.
Creative is the lever that spent two decades without dashboards, logs or an owner, because media produced data while creative produced files. Cheap generation made creative easy to vary. Outcome pricing gave each variant a score. Audited delivery makes that score worth reading.
What this means, by seat
- Brand budgets: the reach and frequency playbook still works, and it should be priced as reach. The moment a performance expectation attaches to the budget, the job needs creative variants, outcome attribution and iteration capacity.
- Agencies: adaptation math is both the margin problem and the pitch. Client version counts keep climbing, and whoever absorbs that workload without doubling headcount keeps the retainer. Evaluate platforms on production capacity per dollar, not CPM alone.
- App and performance UA teams: you are the natural first movers, with deterministic events, an MMP and a testing culture already in place. Those habits are still rare on TV screens, which is what makes them an advantage there. Wire attribution before the first dollar and judge the channel on marginal outcomes rather than average ROAS.
Three questions worth asking this quarter
Take these into the next platform conversation.
- Where did it run? Site-level delivery, per campaign, in writing rather than in a QBR slide.
- What was the invalid traffic rate, and is it already in the price? Fraud protection has stopped being an upgrade.
- Which business outcome does the reporting reach, and how is the match made? If the answer stops at completion rate, the purchase is reach.
A vendor that answers all three is worth paying a premium to. A vendor that answers none is selling something cheaper than it looks.
That cycle is what Starti is built to run: an AI agent that makes the creative with campaign context intact, placement on premium streaming reported at site level, and results tied to installs and revenue rather than plays. How the delivery side gets reported is documented in inventory and traffic quality.
FAQ
What are the biggest CTV advertising trends in 2026?
Budget fragmentation, cheap generation, delivery under audit, outcome pricing, and disclosure law.
Is CTV advertising still growing in 2026?
Yes. CTV is projected to reach $29.3 billion in U.S. ad spend in 2026, up about 11%. What changed is the ranking: social video, estimated at $31.9 billion and up 13%, overtook CTV in 2025 and is projected to stay ahead in 2026.
What is cost-per-outcome CTV advertising?
A pricing model where the advertiser defines the conversion, an install, a signup or a purchase, and pays when it happens rather than paying for impressions. tvScientific sells CTV this way, and performance-priced vendors tie media cost to the same events.
How can an advertiser verify where CTV ads ran?
Ask for site-level delivery reporting per campaign, invalid traffic rates supplied in writing, and an attribution path that reaches a business outcome. Only 33% of buyers report high confidence in inventory transparency on open exchanges, so the question is worth asking before the budget moves.
Sources
- IAB, 2026 Digital Video Ad Spend & Strategy report (published July 14, 2026), with Advertiser Perceptions and Guideline
- New York S8420-A / A8887-B, signed December 11, 2025, effective June 9, 2026
- MNTN, QuickFrame AI 3.0 release, May 5, 2026
- tvScientific, cost-per-outcome buying